Form 144 : Quarterly Statement for TDS on Payments to Non-Residents.
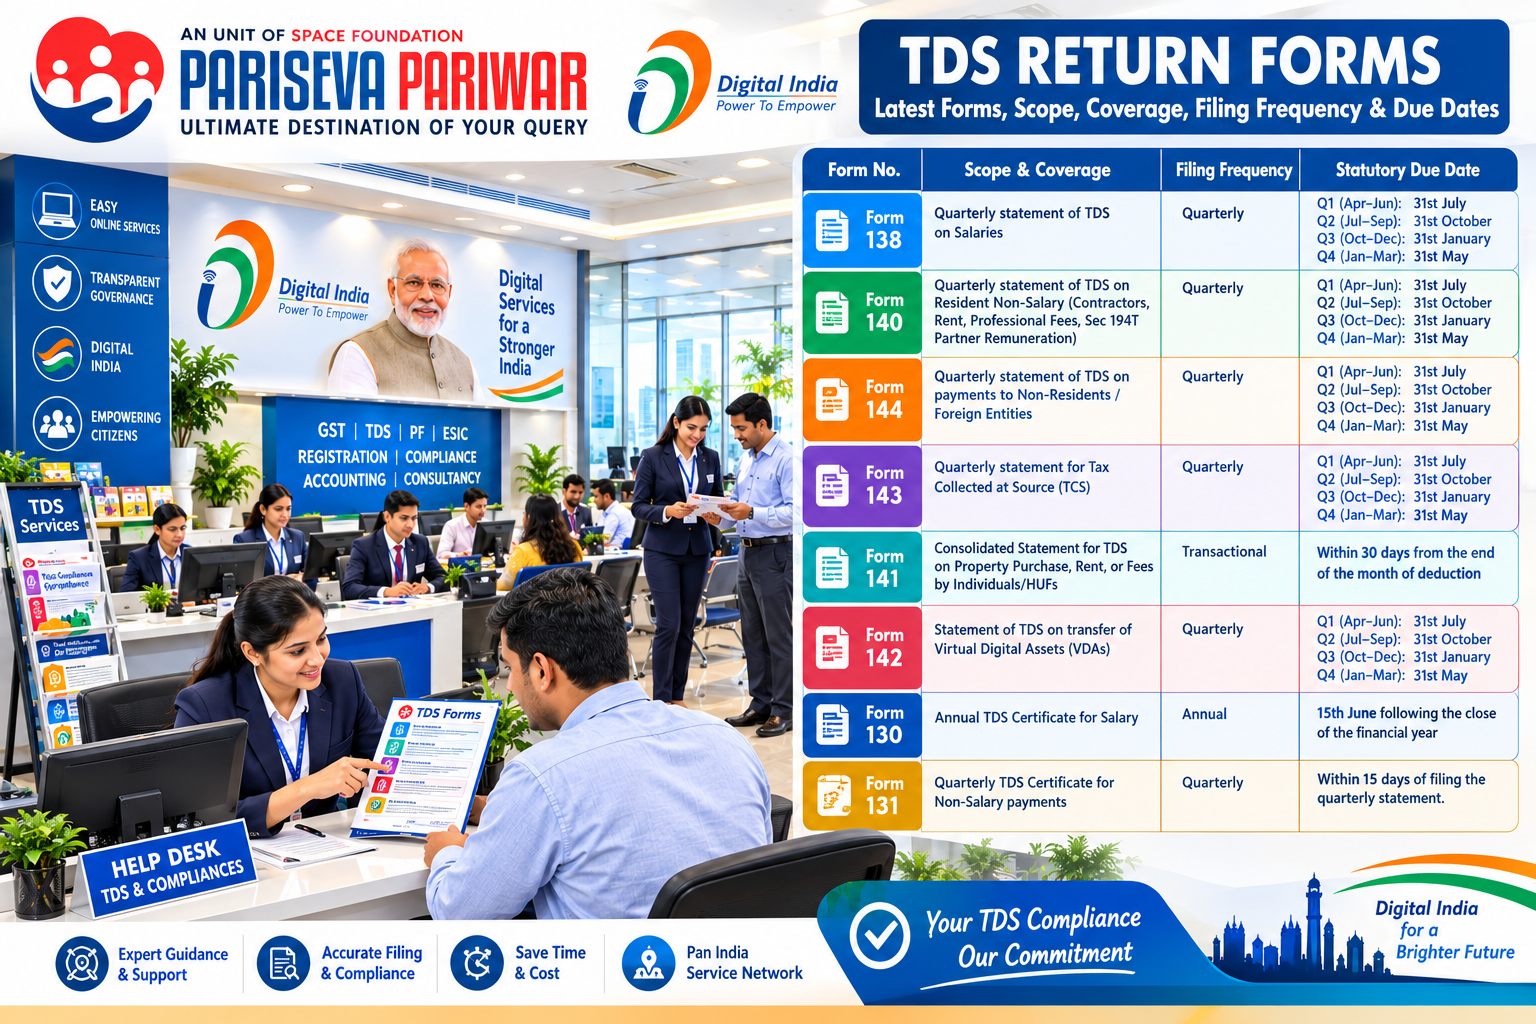
Form 144 is a quarterly TDS statement filed by deductors for tax deducted on payments other than salary made to non-residents, including NRIs and foreign companies. It reports payment details, tax deducted, and tax deposited under Section 397(3)(b) of the Income-tax Act, 2025.
Price on enquiry
2. TDS Deduction Date
TDS must generally be deducted at the time of crediting the payment to the recipient or making the payment, whichever occurs earlier, subject to the applicable statutory provisions.
Examples of covered payments include:
- Interest paid to non-residents.
- Royalty payments.
- Fees for technical services.
- Dividends and other specified income.
- Other payments to non-residents subject to TDS.
The applicable rate depends on the nature of income, the recipient's status and eligibility for benefits under an applicable Double Taxation Avoidance Agreement (DTAA).
3. Form No. 144 Return Filing Due Dates
Quarter Period Covered Return Filing Due Date
Q1 April – June 31 July
Q2 July – September 31 October
Q3 October – December 31 January
Q4 January – March 31 May of the following year
These are the prescribed quarterly filing deadlines under Rule 219. Income Tax Department
4. Documents Checklist
S. No. Document / Information Required
1 TAN of the deductor
2 PAN and registration details of the deductor
3 Name and address of the non-resident recipient
4 Foreign Tax Identification Number (TIN), where applicable
5 Passport or incorporation details, where relevant
6 Nature and purpose of payment
7 Agreement or contract with the non-resident
8 Invoice and payment details
9 Date of credit and date of payment
10 Amount paid or credited
11 TDS rate and tax calculation
12 TDS challan and payment identification details
13 Tax Residency Certificate (TRC), where applicable
14 Form 10F, where applicable
15 DTAA benefit details and supporting documents, if claimed
16 Lower or nil deduction certificate, where applicable
17 Remittance documents and bank advice, where relevant
18 Previous quarter's return acknowledgement and correction details, if applicable
The Income Tax Department's prescribed form and guidance should be consulted for the complete requirements applicable to each transaction.
5. TDS Payment Due Date
For non-government deductors, TDS is generally deposited by the 7th day of the following month. Tax deducted in March is generally due by 30 April, subject to applicable rules and exceptions.
How we can help
Share your requirements and our team will contact you to discuss the service, eligibility, documents and next steps.