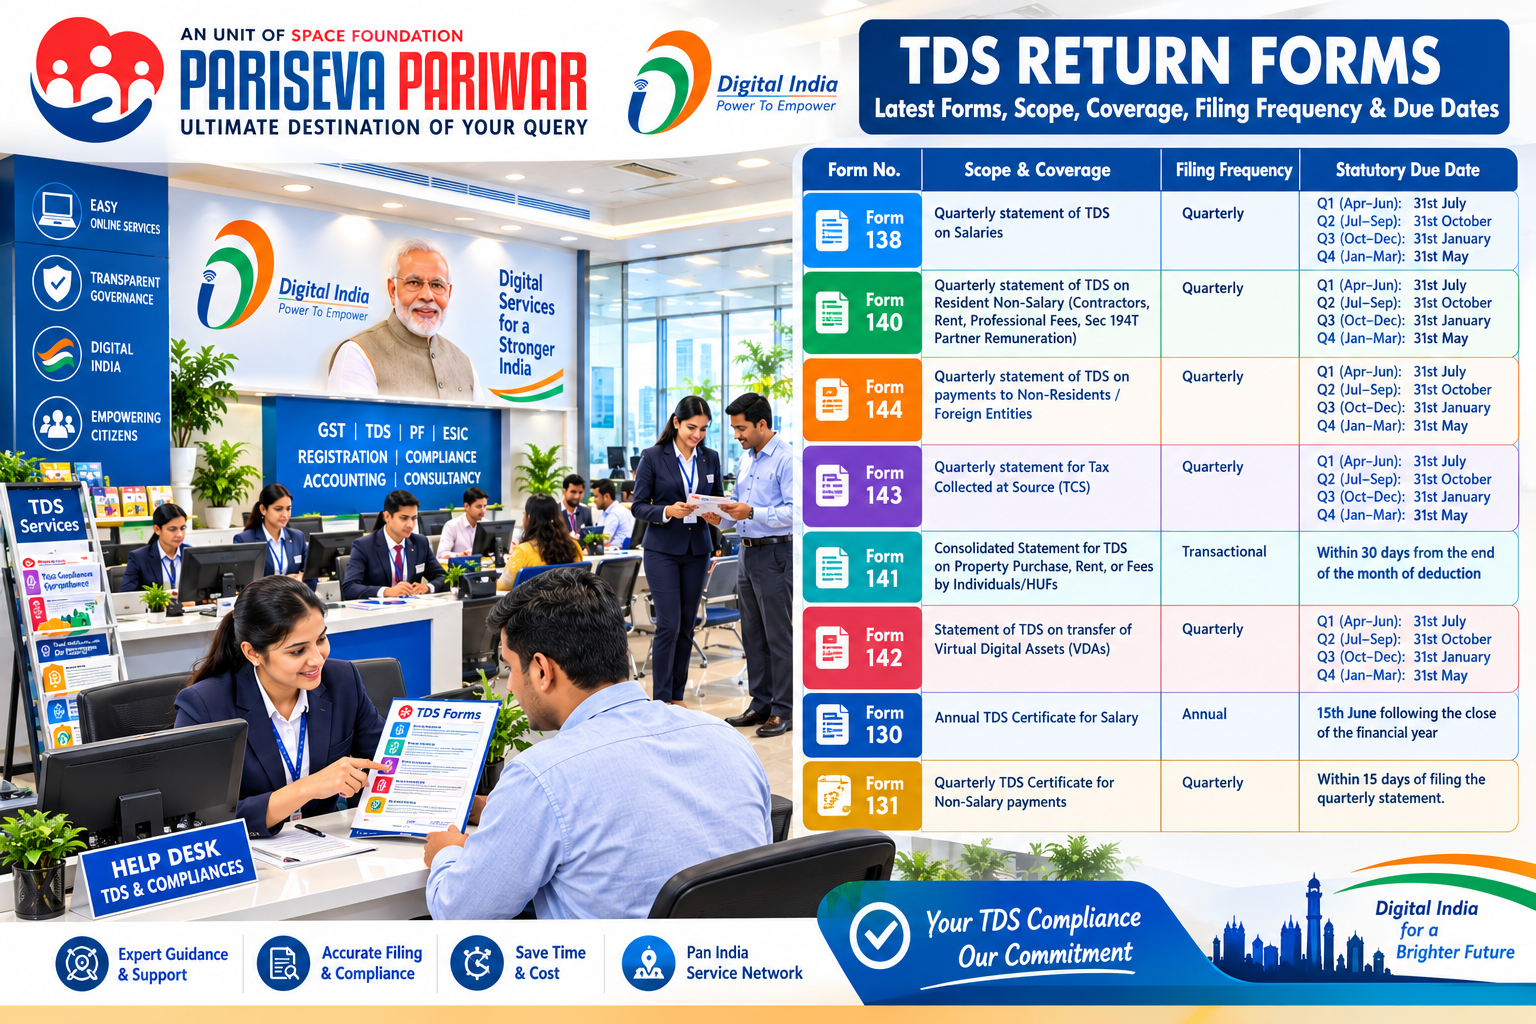
• Form 138 : Quarterly Statement for TDS on Salaries
Form No. 138 – TDS on Salaries Quarterly TDS Return 1. Meaning and Definition Form No. 138 is a quarterly TDS statement filed by employers to report tax deducted at source from salaries paid to employees under Section 392 of the Income-tax Act, 2025. It contains details of employees, salary paid, taxable salary, tax calculation, TDS deducted and deposited with the Central Government.
Price on enquiry
1. Meaning and Definition
Form No. 138 is a quarterly TDS statement filed by employers to report tax deducted at source from salaries paid to employees under Section 392 of the Income-tax Act, 2025.
It contains details of employees, salary paid, taxable salary, tax calculation, TDS deducted and deposited with the Central Government.
Specified banks are also required to report eligible pension and interest income paid to specified senior citizens under Section 393(1).
Applicable provisions:
- Section 392 – TDS on salary.
- Section 397(3)(b) – Furnishing of TDS statements.
- Rule 219 of the Income-tax Rules, 2026 – Filing of Form No. 138.
2. Who Is Required to File?
- Private Limited Companies and Public Limited Companies.
- Partnership Firms and LLPs.
- Proprietorship Businesses.
- Trusts, Societies and NGOs.
- Government Departments and Authorities.
- Other employers deducting TDS from employees' salaries.
- Specified banks in applicable senior-citizen cases.
Applicability: When TDS is deducted from salary under Section 392, the employer must file Form No. 138 for the relevant quarter.
3. Documents & Information Checklist
The following documents and information are required for preparing Form No. 138.
S. No. Documents / Information
1 TAN of Employer / Deductor
2 PAN of Employer / Deductor
3 Name, address and contact details of employer
4 PAN of all employees
5 Employee-wise salary register
6 Monthly salary payment details
7 Employee joining and resignation details
8 Salary structure and allowances breakup
9 Details of eligible exemptions and deductions
10 Employee investment declarations and supporting proofs
11 Previous employer salary and TDS details, wherever applicable
12 Tax computation of each employee
13 Monthly TDS deduction details
14 TDS payment challans
15 Lower / Nil deduction certificate details, if applicable
Additional information for Q4:
- Annual salary computation of each employee.
- Total taxable salary.
- Total deductions and eligible exemptions.
- Tax rebate, wherever applicable.
- Final tax liability and total TDS deducted.
4. Payment of TDS Challan
The employer must deposit the TDS deducted from employees' salaries into the Central Government account.
TDS Deposit Due Dates
Month of deduction Deposit due date
April to February 7th of the following month
March 30th April
5. Form No. 138 Return Filing Due Dates
Quarterly Filing
Quarter Period Covered Return Filing Due Date
Q1 April – June 31st July
Q2 July – September 31st October
Q3 October – December 31st January
Q4 January – March 31st May
How we can help
Share your requirements and our team will contact you to discuss the service, eligibility, documents and next steps.